Money is changing. People still use cash, bank transfers and debit cards, but digital financial services have created new ways to store and move value.One of these developments is the growth of stablecoins, a type of digital token designed to maintain a relatively stable value by being linked to another asset, often a currency such as the US dollar.CBN stablecoin capital requirement
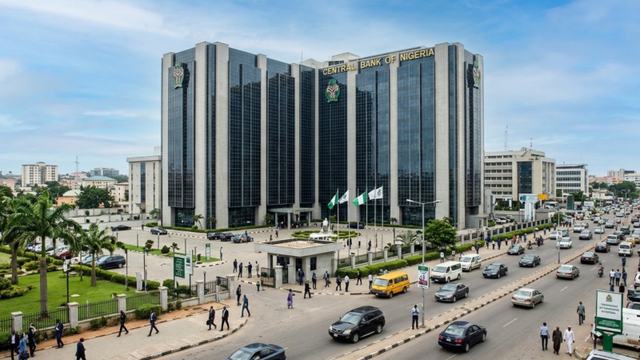
Now the Central Bank of Nigeria has proposed new capital requirements for companies that issue and provide services involving certain digital assets. A report published on November 7, 2026, says foreign-currency-backed stablecoin issuers would face a proposed minimum paid-up capital requirement of ₦15 billion.
Read: Do you need a professional writer in 72 hours? Contact Auxi Chat
For me, this development raises two important questions. How can stronger rules protect people who use digital financial services? And could the cost of meeting those rules make it harder for smaller businesses to enter the market?
READ: Indorama Fertiliser Expansion Targets 5.6 Million Tonnes
The answers matter because digital finance can create opportunities, but customers also need to understand the risks before trusting a company with their money.
What the CBN stablecoin capital requirement Rules Say
Read: Need a professional website in 72 hours? Contact Auxi Chat
The Central Bank of Nigeria’s proposed framework sets different capital requirements for different types of virtual asset businesses.
Under the proposal reported on November 7, companies issuing naira-referenced stablecoins would need at least ₦10 billion in paid-up capital. Issuers of foreign-currency-referenced stablecoins would face a proposed minimum of ₦15 billion.
Other virtual asset service providers, including exchanges, custodians, wallet operators and payment service providers, would face a proposed minimum capital requirement of ₦1 billion.
The proposal also includes requirements concerning licensing, reserves, reporting and the operation of businesses in Nigeria.
These are proposed rules, so their legal status and final requirements should be checked against the CBN’s official regulatory documents before publication or before a company makes business decisions based on them.
The different capital levels reflect the fact that not every digital asset business performs the same function. A company issuing a stablecoin may have responsibilities that differ from those of a business providing a wallet or another service.
The purpose of capital requirements is generally to ensure that a financial business has resources to support its operations and manage certain risks. But the appropriate level and effect of a requirement depend on the details of the rules and the business involved.
What Is a Stablecoin?
A stablecoin is a digital token designed to keep its value linked to another asset. Some stablecoins are linked to the US dollar, while others are linked to different currencies or assets.
A simple example can help explain the idea.
Imagine a digital token designed to be worth one US dollar. The company issuing it says it maintains reserves intended to support that value and allow customers to exchange the token under the stated rules.
People may use such tokens to move digital value between services or participate in certain financial activities. However, the token’s usefulness and risks depend on how it is issued, what backs it and whether customers can exchange it when they need to.
A stablecoin is not the same thing as money deposited in a Nigerian bank account. A token issued by a private company does not automatically have the same protections as a bank deposit.
Its value may also be affected by problems with reserves, the issuer’s operations, technology failures or restrictions on withdrawals.
This is why clear rules and honest information matter. People should understand what they are buying and what rights they have if something goes wrong.
Why the CBN Wants Capital Requirements
A company that issues a digital token must be able to manage its operations and meet the obligations set out in its rules.
Capital requirements can help establish a financial foundation for that business. They may also make it easier for regulators to assess whether an operator has sufficient resources for the activities it wants to carry out.
The proposed Nigerian framework also addresses reserve management and redemption arrangements. These are important because a stablecoin that claims to maintain a fixed value needs a credible way to support that claim.
If a token is intended to track the US dollar, for example, customers need to understand how the issuer supports the token and what happens when they want to exchange it.
The proposed rules seek to strengthen oversight and make operators more accountable. However, the effect will depend on how the requirements are implemented and how regulators supervise the businesses involved.
Stronger rules do not remove every risk. Customers still need to understand the nature of digital assets, and companies still need sound systems and responsible management.
How the Proposed ₦15 Billion Rule Could Affect Businesses
The proposed minimum capital requirement could make it more expensive to start or operate a foreign-currency-backed stablecoin business in Nigeria.
A large, well-funded financial company may find it easier to meet such a requirement than a small start-up with limited funding.
Smaller businesses may need to raise more capital, find partners, change their business models or decide that entering the market is no longer practical.
That could affect competition. If fewer businesses can afford to meet the requirements, the market may become more concentrated among larger operators.
On the other hand, supporters of stronger capital rules may argue that financial services need firms with sufficient resources to manage risks and protect customers.
These two concerns need to be considered together. Rules should aim to reduce risks without creating unnecessary barriers that prevent useful innovation.
The final impact will depend on the requirements that are ultimately adopted, the transition period and how the rules apply to different kinds of businesses.
What the Proposed Reserve Rules Mean
Capital is only one part of the proposed framework. Reserve management is also important for stablecoins that claim to maintain a link to a currency.
A reserve is made up of assets held to support the issuer’s obligations. Customers need to know what those assets are, how they are managed and whether they can support redemptions.
The proposed framework includes rules intended to separate customer backing funds from the issuer’s ordinary business spending. It also addresses the management of reserves and the conditions under which new tokens can be issued.
These measures are designed to reduce the risk of a company issuing more tokens than it can properly support.
The proposal also states that stablecoin holders should not automatically receive interest, yield or dividends simply because they hold the tokens.
Customers should understand that holding a stablecoin is different from placing money in a savings account. The rights and risks depend on the product and the applicable rules.
Before using a digital token, a person should examine the issuer, the terms, the redemption process and the protections available if the service fails.
What Nigerian Customers Should Know
The proposed capital rules are mainly directed at businesses, but customers may feel the effects of changes in the digital asset market.
If operators must spend more money to comply with regulations, their costs could rise. Depending on the business and competition, some costs may affect the prices or services offered to customers.
Some operators may decide not to enter the market. Others may invest in stronger systems and compliance processes.
However, it would be premature to say that the proposed rules will definitely make stablecoins more expensive or remove particular services from Nigeria. Those outcomes depend on how the final framework works in practice.
Customers should also avoid assuming that a stablecoin is risk-free simply because it is linked to a currency.
They should check whether the issuer is properly authorised where required, understand how the token can be redeemed and avoid putting money into a product they do not understand.
They should be particularly cautious of anyone promising guaranteed profits or asking them to transfer money without explaining the risks.
READ: Bank Fraud in Nigeria Raises New Concerns About Digital Banking Safet
Could the Rules Help Nigeria’s Digital Finance Sector?
Nigeria’s digital finance sector includes banks, payment companies, technology firms and businesses working with digital assets.
Clear regulation can help businesses understand what is expected of them. It can also give customers more information about the standards operators must meet.
But regulation must be practical. Requirements that are too difficult to meet may discourage smaller companies, while weak requirements may fail to address important risks.
The challenge is to create a framework that protects customers, encourages responsible innovation and allows legitimate businesses to compete.
The proposed stablecoin rules could become an important part of that discussion. Their success will depend on clear implementation, effective supervision and a fair process for businesses that must comply.
What Happens Next?
The next step is to establish the final form and timing of the proposed framework.
Businesses will need to understand the capital requirements, licensing conditions, reserve rules and transition arrangements that apply to their activities.
Customers should pay attention to official announcements rather than relying on social media summaries that may leave out important details.
The distinction between a proposal and a rule that is already in force matters. Companies should not assume that every reported provision has become a final legal obligation without checking the official documents.
The CBN’s proposal signals a continuing effort to define how certain digital asset businesses should operate in Nigeria. But its practical effects will become clearer as the regulatory process develops.
A New Chapter for Digital Finance in Nigeria
The proposed ₦15 billion capital requirement for foreign-currency-backed stablecoin issuers has brought fresh attention to the future of digital finance in Nigeria.
For regulators, the challenge is to protect the public and make sure that companies can meet their obligations. For businesses, the question is how to comply while remaining competitive. For customers, the priority is understanding the products they use and the risks they take.
I believe the most useful way to view the proposal is to recognise both sides. Stronger safeguards can support confidence, but the cost of compliance may also influence who can operate in the market.
The final outcome will depend on the details of the rules and how they are enforced.
For now, customers should remain careful with digital assets, businesses should study the proposed requirements, and readers should distinguish between a new proposal and a rule that has already taken effect.
The future of digital finance will depend not only on new technology, but also on trust, responsible management and clear protections for the people who use it.
The writer of this article does not claim to know the individuals named personally. The information regarding their backgrounds as published on Global News Arena is based on independent online research.
If you have an article, opinion piece, event or news story you would like published, Global News Arena would love to hear from you.